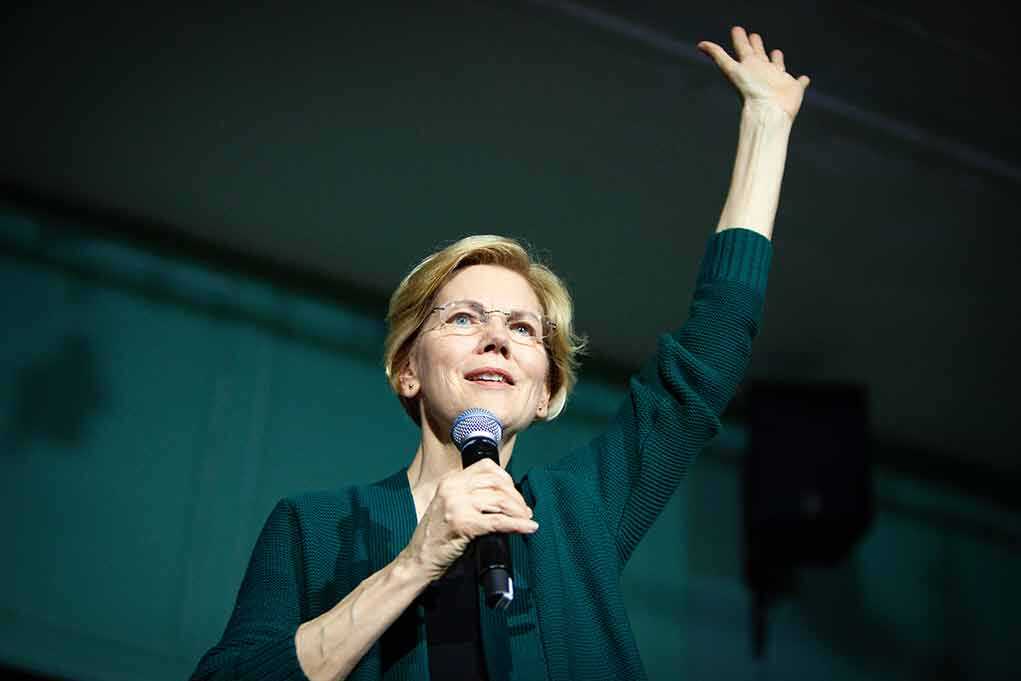
Senator Elizabeth Warren’s latest attack on Treasury policy hit a wall as Secretary Scott Bessent fired back with data, deficits, and a reminder of who fueled the inflation spike in the first place.
Story Highlights
- Warren blamed rising Treasury yields for higher mortgage, car, and credit-card costs.
- Bessent countered that yields reflect many forces, including large deficits and global pressures.
- Treasury doubled long-bond buybacks; yields dipped briefly, then rebounded near prior levels.
- Bessent said buybacks preserved market function and that yields might have been higher without them.
What Warren Claimed About Yields And Family Budgets
Senator Warren wrote Treasury on October 7 saying rising Treasury yields were “self-inflicted” and driving up costs for mortgages, car loans, and credit cards. She pointed to the 10-year yield near levels last seen two decades ago and tied the move to a recent Federal Reserve rate hike. Her letter warned of pressure on family budgets as borrowing costs rose across the board for households and small businesses.
Warren also pressed for details on Treasury’s bond buybacks, implying the program was meant to suppress long-term rates. She argued that the spike in yields after the rate move showed policy error. Her push fit a pattern where political figures pick one cause for a complex market shift. That claim drew fast scrutiny, because bond yields reflect expected future short rates, inflation trends, investor risk premiums, and the vast federal borrowing need, not a single lever.
How Bessent Answered: Deficits, Global Forces, And Market Plumbing
Secretary Bessent rejected the “self-inflicted” label and said yields rose for many reasons. He cited global pressures and the hard math of America’s deficit as key drivers. He said long-dated yields had moved near two-decade highs but called that jump out of line with the strength of the United States economy. He argued that the rise did not come only from a single rate decision by the Federal Reserve.
Bessent defended Treasury’s buyback move as market maintenance, not a magic switch. Treasury doubled planned buybacks of longer bonds to support liquidity and price discovery in strained trading. That kind of action narrows gaps and steadies auctions. Reporters noted the 10-year yield fell for a time after the news, yet later climbed back near earlier marks as fresh inflation fears and supply concerns reappeared in markets.
Did Buybacks Work? The Immediate Dip And The Bigger Picture
Coverage showed an initial drop in long yields when buybacks expanded, including a quick six-basis-point move in the 10-year before later reversal as headlines shifted. That short response signaled traders heard the message but were not ready to ignore larger forces. Those forces included sticky inflation expectations, heavy Treasury issuance, and risk premiums that investors demand to hold long bonds during uncertain times.
Bessent said the test is the counterfactual: where would yields be without action. He pointed to successful Treasury auctions afterward as evidence that confidence held, even as global shocks and deficit math kept pressure on term premiums. He stressed that buybacks aim to keep markets working so the government can fund at the best available rate day to day, not to override the entire yield curve by decree.
Competing Stories: Blame The Fed Or Blame The Spending?
Warren focused on the Federal Reserve’s latest hike and called the yield surge “self-inflicted.” That frame skips other drivers that analysts and officials flagged. Bessent noted that deficits matter for long yields and said global issues helped push rates higher. He also reminded Warren that the worst inflation burst and the steep rise in the policy rate followed the prior administration’s spending spree that she supported.
Independent reports echoed the split view. Some highlighted that consumer borrowing costs track Treasury yields. Others showed yields rising again after the buyback bounce as inflation expectations lifted on tariffs and supply shocks. That mix undercuts any one-cause story. The sober read is simple: long rates move on expectations for future short rates, inflation, and the premium investors charge for risk. Policy can help on the margins, but deficits and confidence set the tone.
Why This Fight Matters For Your Wallet
Higher long-term yields make monthly payments bigger for families and for the government. That is why market trust and smaller deficits are vital. A lean government lowers pressure on rates. A clear energy plan brings supply and price stability. A strong dollar and secure borders reduce shocks that rattle markets. Those steps line up with conservative values of discipline and order and can ease the term premium that lenders bake into every long loan you take.
Bottom Line: Facts Over Theater
Warren sent more than one hundred letters, but her latest broad-brush blame misses the full picture. Bessent answered with a case rooted in deficits, global forces, and market function. Treasury buybacks gave brief relief and kept auctions steady, but they cannot erase the cost of years of overspending. The path to lower rates runs through restraint, reliable energy, and growth that beats inflation. That is the hard, adult work that protects your paycheck and the Constitution’s promise of limited government.
Sources:
foxbusiness.com, cnbc.com, thegatewaypundit.com, apnews.com, aol.com, fortune.com, nytimes.com, finance.yahoo.com, frbsf.org