House records show Ilhan Omar’s household business jumped to millions on paper, then fell to zero as the winery shut down days after she amended her filing.
Story Highlights
- House disclosures first showed a large spike in the value of a winery tied to Rep. Ilhan Omar’s spouse, then later listed no net value after liabilities.
- Committee Chair James Comer requested financial records and communications tied to the winery and a related firm.
- California records show the winery dissolved shortly after the amended filing and Comer’s request timeline.
- A federal prosecutor confirmed a probe into Omar’s financial disclosures, according to published reporting.
Disclosures Show Sharp Rise And Rapid Reversal In Reported Values
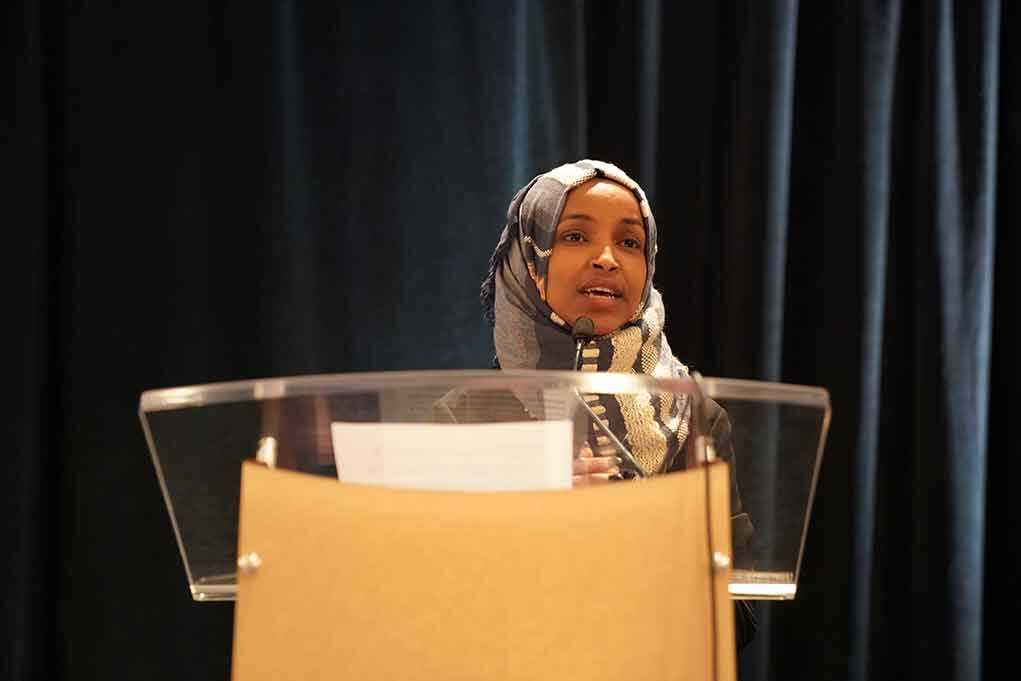
House financial disclosures identified eStCru LLC as a Santa Rosa winery held by Rep. Ilhan Omar’s spouse. The 2024 disclosure initially put eStCru in the $1,000,001 to $5,000,000 range, after it appeared in a much lower range the prior year. The filing also reported income from the winery. Omar later amended the disclosure. The amended filing listed eStCru and Rose Lake Capital at no net value after liabilities and reduced the couple’s aggregate assets to a far lower band.
Reporting summarized the combined swing across both businesses. Coverage said the total reported asset range moved from roughly tens of thousands in 2023 to as high as tens of millions in 2024 before the amendment brought it down. That eye‑catching jump, followed by a steep revision, triggered calls for records. Omar’s office has said the original numbers relied on incomplete accountant information and failed to subtract liabilities, and that the amendment corrected the record.
Oversight Inquiry Targets Records, Not Just Valuation Bands
House Oversight Chair James Comer sent a February 5 letter to Timothy Mynett, Omar’s spouse, seeking financial records and communications for eStCru and Rose Lake Capital. Comer cited the valuation change and asked for documents that could show who invested, what money moved, and whether influence was sought through the businesses. That request centered on bank records, investor agreements, and related communications, expanding the review beyond a simple paperwork mistake claim.
Published accounts state Comer’s request built a concrete timeline that investigators can test. The committee’s document seek aims to verify ownership interests, liabilities, and how the initial valuation was calculated. That level of detail matters because private-company values on House forms use broad ranges and can reflect different methods. Records like ledgers, tax returns, and investor contracts can show whether the numbers reflected debt, an estimate error, or something else entirely.
Winery Dissolves Days After Amendment Amid Growing Scrutiny
California business records reported that eStCru LLC dissolved on April 4. Reports noted that date came shortly after the amended disclosure and roughly two months after Comer’s February request to Mynett. The close timing does not by itself prove why the company closed, but it places the shutdown inside the same window as the committee’s inquiry and the public revision of asset values.
ILHAN OMAR — WINERY FINANCIAL QUESTIONS
Rep. Ilhan Omar’s husband co-owned eStCru LLC, a California wine business that filed for termination in April 2026.
Earlier congressional financial disclosures valued his interests in eStCru and Rose Lake Capital at up to $30 million…
— Truthsleuth (@sleuthprocess) October 20, 2026
Separately, published reporting said a federal prosecutor confirmed a probe into Omar’s financial disclosures. That development raises the stakes for record retention and transparency. It also increases pressure for clear answers about how the original multi‑million dollar figures were set, what liabilities existed, and what investors, if any, were told. One sentence of caution: an investigation or dissolution alone does not equal a legal finding of fraud.
Why This Matters For Accountability And Honest Markets
Congress requires members to disclose assets, income, and liabilities so the public can spot conflicts of interest. When a household business jumps from thousands to millions, then falls to zero after liabilities, people deserve a clear, documented explanation. Taxpayers expect accurate filings, not guesswork. Investors expect that a business selling stakes or products keeps real books and real inventory. Transparent records are the only way to protect families, retirees, and small savers from slick numbers on paper.
For conservatives, this case highlights why oversight must be firm and prompt. President Trump’s administration has pushed for law and order, and Congress should back that with targeted subpoenas and fast timelines. If liabilities wiped out value, documents should prove it. If the valuation was wrong, show the work and fix it. If influence buyers were circling, expose it and stop it. Sunlight protects the Constitution’s promise of equal treatment under the law.
What Comes Next: Documents, Depositions, And A Paper Trail
Investigators can resolve key questions by obtaining full original and amended House filings, detailed business ledgers, bank statements, tax returns, investor lists, and dissolution papers. They can review storage, production, and shipping records to match any claimed inventory to actual goods. They can depose owners, accountants, and custodians about who calculated values, what liabilities existed, and why the company dissolved when it did. Facts on paper will tell the story better than spin.
The public should expect a line‑by‑line reconciliation that matches every valuation to evidence. That is fair to Rep. Omar, fair to investors, and fair to voters. If the numbers were innocent but sloppy, the record will show it. If they were reckless or worse, the record will show that too. Either way, strong oversight serves honest enterprise and defends families who play by the rules and just want the truth without delay.
Sources:
twitchy.com, dallasexpress.com, newsweek.com, theepochtimes.com, timesnownews.com, academic.oup.com, sec.gov